
Share on
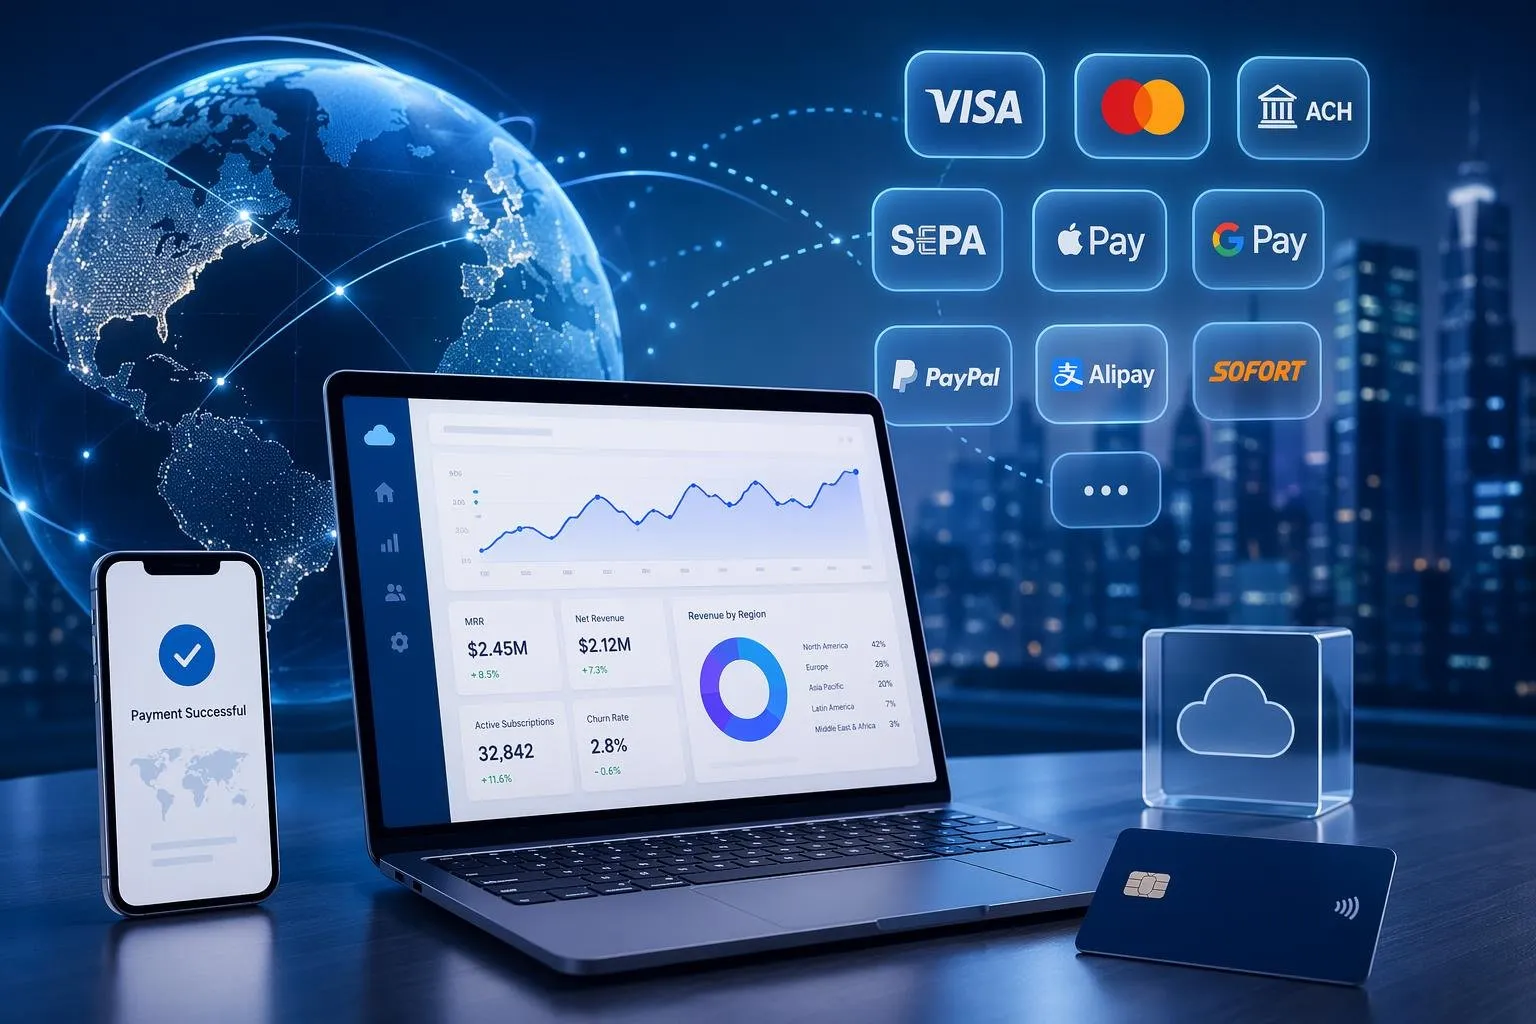
Cross-border B2B payments are transactions between businesses in different countries. They can involve a buyer paying for a service, a company paying an overseas supplier, or an entity moving funds within a corporate group. The useful starting point is not a list of rails or providers. It is a clear definition of who is paying whom, what event triggers the payment, which currency obligation exists, and which team owns the result when the payment is delayed, rejected, or disputed.
That distinction matters because B2B payments carry commercial and operational context that consumer payments often do not. A payment may be linked to a purchase order, an invoice, a delivery milestone, a subscription renewal, a supplier relationship, or an intercompany accounting entry. A workable design connects that context to the payment lifecycle from the beginning.
How Cross-Border B2B Payments Differ From Consumer Payments
B2B payments are not simply larger versions of consumer transactions. The parties may have negotiated payment terms, agreed on a billing currency, and need documentation that passes through finance, procurement, accounting, risk, and operations. A payment can be successful in one system while still leaving an unresolved question elsewhere: whether a buyer should receive access, whether a supplier invoice is paid, or whether finance can reconcile the resulting cash movement.
The first decision therefore concerns the business event behind the transaction. A one-time online purchase, a recurring software invoice, a milestone-based service agreement, and a supplier disbursement may all cross a border, but they should not automatically use the same payment logic.
Start by Separating the Payment Direction
Cross-border payment design becomes clearer when teams separate the direction of money movement before comparing providers.
Payment direction | Typical business event | Primary owner | Questions to resolve first |
Customer collection | A business customer pays for software, services, goods, or a renewal | Commercial, product, payments | How will the buyer see price, select a method, complete payment, and receive confirmation? |
Supplier or contractor payment | A business pays an overseas vendor, contractor, or service provider | Finance, procurement, AP | Which approval, beneficiary data, invoice, currency, and status controls are required? |
Intercompany movement | Related entities move funds to support operations or settle internal obligations | Treasury, finance, legal | What is the entity purpose, accounting treatment, approval path, and documentation requirement? |
This is more than a labeling exercise. Customer collection is usually designed around the buyer journey and order or account state. Supplier payments are often designed around invoice approval, beneficiary verification, and cash-management controls. Intercompany movement can bring additional treasury, accounting, and legal requirements. Mixing them into one provider scorecard makes it harder to see the actual risk and ownership model.
Select a Payment Path From Transaction Facts
Once the direction is clear, choose a payment path from the facts of the transaction rather than from a generic list of payment methods.
Start with four questions:
- Who is the payer and who is the recipient, and how is each party identified?
- What currency is the commercial obligation expressed in, and who carries any conversion exposure?
- Is payment initiated at checkout, from an approved invoice, under a recurring schedule, or after a delivery milestone?
- What does the business need to know before it releases goods, activates service, marks an invoice paid, or closes the period?
The answers guide the rail and interface decision. A business customer completing an online order may need a clear checkout journey and an explicit return from the payment flow. An approved supplier invoice may need payment instructions, structured remittance data, and approval evidence. A recurring B2B software charge may require a different plan for authorization, retries, notifications, and subscription state. The rail is important, but it is only one part of the design.
Build a B2B Cross-Border Payments Decision Matrix
Use a shared decision matrix before committing to a payment connection or operating model.
Decision area | What to decide | Evidence to gather | Failure mode if it is ignored |
Transaction direction | Whether the journey is collection, payout, or intercompany | Contract type, invoice or order flow, entity map | The team evaluates the wrong provider category or misses a required control |
Currency model | Invoice currency, payer currency, recipient currency, and conversion owner | Contract terms, margin sensitivity, customer or supplier expectations | Finance cannot explain differences between the commercial amount and the settled amount |
Payment initiation | Checkout, invoice approval, scheduled billing, or batch workflow | User journey, approval policy, system of record | The payment status does not map cleanly to the business event |
Status model | Which state unlocks fulfillment, service access, accounting, or follow-up | Order, billing, support, and finance process maps | Teams act on a payment too early or chase a payment that is still pending |
Exception ownership | Who resolves bad details, rejects, reversals, refunds, returns, or disputes | Current incident log and role matrix | Exceptions sit between teams and customer or supplier communication becomes inconsistent |
Data and reporting | What references, timestamps, and reason codes must travel with the payment | Reconciliation needs, audit requirements, support workflows | Manual investigation grows as transaction volume increases |
The matrix is deliberately neutral about providers. It helps a team distinguish a requirement from a marketing claim and evaluate whether an option fits the real operating model.
Treat Costs as an End-to-End Operating Question
Cross-border cost is not limited to a visible transaction charge. It can include conversion treatment, intermediary deductions, return or correction work, manual reconciliation, customer or supplier support, and the internal time spent resolving payment status. The cost picture changes according to the route, currencies, counterparties, and commercial agreement.
For that reason, compare cost at the level of the full payment event. Ask what amount the payer is shown, what amount the recipient is expected to receive, when each figure becomes known, and which data allows finance to explain a difference. The goal is not to assume that one method is always less expensive. It is to prevent a payment design from hiding a cost or creating a reconciliation task that only appears after launch.
Design the Full Payment Lifecycle
The point at which money is initiated is only the first state in a B2B workflow. A resilient design maps the full lifecycle.
Capture the right payment data at initiation
Store the business references that explain the payment: customer or supplier identity, invoice or order reference, entity, currency, amount, payment purpose, and internal owner. Validate required recipient or payer details at the earliest practical point. Structured data reduces the likelihood that a payment status later becomes detached from the commercial relationship it represents.
Define status ownership and fulfillment rules
Agree what each payment state means to each function. A pending payment may mean that a buyer needs a reminder, a supplier payment awaits confirmation, or a finance team must wait before closing an item. A successful initiation is not necessarily the same as an available balance, completed settlement, fulfilled order, or reconciled receivable. Name the event that changes each business state and the team that owns it.
Prepare exception and reconciliation paths
Test more than the ideal payment. Teams should know how they will respond to a rejected payment, missing beneficiary detail, delayed confirmation, duplicate message, return, refund, dispute, or a mismatch between payment and invoice data. Define what support can tell a counterparty, what operations can repair, and what finance needs to reconcile the event. This is where a payment design becomes operational rather than merely technical.
Compare Providers by the Operating Model You Need
The phrase B2B cross-border payment fintechs often groups together very different kinds of businesses. A bank service, a payment-acceptance provider, an AP platform, and a coordination layer can all be relevant, but they answer different problems.
Provider category | Usually best assessed for | Evaluation question |
Banking or payment-network service | Moving funds to an identified recipient | Which corridors, currencies, status messages, and correction processes matter to the business? |
AP or spend-management platform | Supplier payment approvals and invoice-linked execution | Does the workflow preserve approval evidence, beneficiary controls, invoice data, and reconciliation context? |
Customer payment-acceptance provider | Online buyer checkout, customer payment methods, and payment confirmation | Does the checkout and payment-status design fit the buyer journey and internal order logic? |
Payment coordination or orchestration layer | Managing multiple connections, configuration, routing, and transaction operations | Can the team observe, govern, and change the payment stack without creating fragmented processes? |
When evaluating a cross-border B2B fintech, avoid asking only whether it covers a destination or payment method. Ask where it sits in the lifecycle, which party it serves, what data it returns, and which obligations remain with the business. Those questions create a more durable comparison than a feature list.
Run a Controlled Launch Before Scaling
Start with a defined transaction cohort rather than every country, entity, and payment path at once.
- Select one business use case with clear value and named owners.
- Document the payment state map, the customer or supplier communication, and the reconciliation path.
- Test successful, pending, rejected, duplicate, correction, and refund or return scenarios that are relevant to the flow.
- Measure the outcome using completion, exception volume, time to usable status, reconciliation effort, and support demand.
- Expand only after the team can explain the operating result and maintain the controls.
This approach keeps international growth from becoming a collection of disconnected payment connections. It also gives teams the evidence needed to decide whether a problem is in the commercial model, checkout, data, operations, or provider setup.
Where Antom Fits in a B2B Cross-Border Payment Conversation
When a B2B business collects customer payments through an online buyer journey, Antom Checkout Payment is a product option to assess as part of the checkout, payment-method, and status-design discussion. Its fit should be validated against the buyer markets, transaction types, and business workflow involved.
For organizations assessing how multiple payment connections and operational rules should be coordinated, Antom Payment Orchestration can be considered in the evaluation of payment routing, configuration, visibility, and change management. Specific product suitability and market availability should be confirmed for the intended deployment.
FAQs
What are cross-border B2B payments?
They are transactions between businesses in different countries. They may support customer collection, supplier payments, contractor payments, or intercompany movement. The appropriate payment design depends on the commercial event, the parties involved, the currency model, and the controls needed after initiation.
How should a business choose a cross-border B2B payment method?
Begin with transaction direction, currency obligation, payment trigger, status requirements, and exception ownership. Then compare payment options by how well they support that specific workflow, including the data needed for customer communication, finance, and reconciliation.
What should a business validate before launching a new cross-border payment flow?
Validate the actual payment path, counterparty or customer eligibility, applicable commercial terms, confirmation behavior, operational roles, data requirements, and jurisdiction-specific obligations. Test normal and exception scenarios before expanding the flow.
Conclusion
The strongest cross-border B2B payment design starts with the business relationship, not the payment rail. Separate customer collection, supplier payment, and intercompany movement; define the currency and status model; map the full lifecycle; and choose providers based on the operating role they need to perform. That makes global payment expansion more deliberate, more observable, and easier to improve.